After collecting $7,000/mo from rental units.
Rent vs buy
Discover the true out-of-pocket cost of owning a 2–4 unit NYC brownstone after rental income and potential tax benefits.
Smooth transaction with limited risk
No pressure to over pay and buy within a certain time period
A team of people that will be with you even after the transaction is complete
Rent vs. own
Owning a multi-unit NYC brownstone is not the same as renting a similar apartment. Tenant rent from the other units can offset a large share of your mortgage, taxes, insurance, and utilities—sometimes bringing your net out-of-pocket cost close to (or below) what you pay in rent today. Enter your numbers below to compare.
After collecting $7,000/mo from rental units.
From 2 tenant-occupied unit(s).
Potential monthly tax benefit ~$3,290/mo.
First-time buyers purchasing 3–4 unit properties under $2M may qualify for as low as 10% down financing options.
Estimated Year-1 deductions associated with the 66.67% rental portion.
Stanley Montfort specializes in helping NYC buyers evaluate 2–4 unit townhouses based on true net cost after rental income.
Tax estimates are educational and illustrative only — not tax, legal, or mortgage advice. Actual deductions depend on basis, land allocation, rental vs. personal use, and passive activity rules. Consult a CPA. Ownership cost estimates are not a guarantee of performance, financing, or rental income.
The tool estimates your gross monthly carrying cost (mortgage principal & interest, taxes, insurance, water, and common utilities), subtracts net rental income from the other apartments, and compares that net ownership cost to your current rent. It also shows illustrative Year-1 rental-related tax deductions so you can see how ownership might look after a theoretical tax benefit.
Your estimated out-of-pocket housing cost after collecting rent from the additional units—not the sticker mortgage payment alone.
Monthly cash flow from tenant apartments that can help pay principal, interest, taxes, insurance, and shared building costs.
Illustrative rental-portion deductions such as mortgage interest, property taxes, insurance, utilities, and straight-line depreciation (27.5 years for residential rental property).
With a conventional condo or rental apartment, you pay 100% of housing costs yourself. With an owner-occupied 2–4 family brownstone, renters help carry the building while you build equity in the entire structure and land—not just a single unit. That is why many NYC buyers discover that a higher purchase price can still produce a competitive monthly cost of living.
Focus on net cost to own vs. current rent, then glance at the illustrative after-tax ownership cost. The tax value figure applies your marginal bracket to estimated Year-1 rental deductions—it is not a guarantee of refunds or reduced withholding. Passive activity rules, personal vs. rental use, basis, and cost segregation can all change the real outcome.
Stanley Montfort specializes in helping NYC buyers evaluate 2–4 unit townhouses based on true net cost after rental income—not just list price. If the calculator shows ownership is close to your rent, the next step is finding buildings where the rents, condition, and financing actually support that outcome.
Book a brownstone strategy call or browse available brownstones.
No. It depends on purchase price, rate, down payment, taxes, insurance, vacancy, and achievable rents. The calculator shows when ownership's net out-of-pocket is lower, similar, or higher than your current rent.
No. Tax figures are educational estimates only. Actual deductions depend on how the IRS treats your rental activity, land allocation, personal use, and your overall tax return. Consult a CPA before relying on after-tax numbers.
Many buyers plan on 20%, but some first-time buyer programs for 3–4 unit homes under certain price caps may allow roughly 10% down. Lender guidelines, reserves, and debt-to-income still apply.
Yes. Even strong buildings have turnover. Building a modest vacancy allowance (for example 5%) keeps the net-cost estimate more realistic.
Tax disclaimer: Educational and illustrative only—not tax, legal, or mortgage advice. Results depend on basis, land allocation, rental vs. personal use, and passive activity rules. Standard residential rental depreciation assumptions are used; no cost segregation. General disclaimer: Estimates only; not a guarantee of performance, financing, tax treatment, or rental income.
Explore the other calculators to pressure-test closing costs, rent vs buy, and ownership choices.
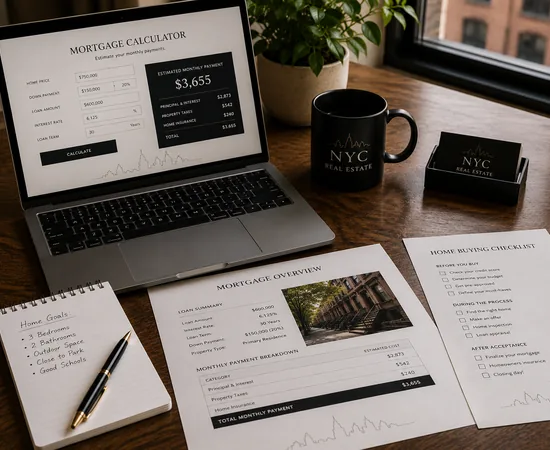
Estimate monthly payment, taxes, and carrying costs before you make an offer.
Open calculator →
Project transfer taxes, attorney fees, and total cash needed to close.
Open calculator →
See net proceeds after commissions, transfer taxes, and seller fees.
Open calculator →Weigh monthly costs between a condo and an income-producing brownstone.
Open calculator →Reach out for buyer representation, listing strategy, or a confidential valuation with Stanley Montfort.